Movie Review: The Amateur

May 17, 2025

Watch it? Rent it? Skip it?

Skip it. That was such a huge waste of a free movie ticket. The Amateur is about a pencil neck, computer geek working for the CIA who becomes an International CIA Agent overnight in order to find and kill those who killed his wife. Sounds stupid? You’re right. It is. It was.

Somehow over a 2 hour period Rami Malek, an academy award winner, is transformed into a bullet proof CIA spy using his skills he learned from Lawrence Fishburne over a period of a few days and the help of YouTube videos (seriously). Jon Berthnal has a couple of very regrettable appearances, seriously, just a couple. Needless to say Rami learns how to hack into every building, access every camera, to evade the highly trained CIA agents sent to find him. He is bulletproof. Literally escaping a Seal team with automatic weapons. Ugh. It is just so cringe worthy.

I feel more stupider just writing this. This was crap. Just total crap. A waste of 2 hours and a free movie ticket. Don’t waste your time or money watching this stupidity. Go watch something better like The Substance.

LOL.


Comments Requested in Support of Insurance Bill

May 16, 2025

As I mentioned a few days ago:

Progressive Insurance sent out a message to home owners and insurance agents in the Bay Area urging them to contact elected officials concerning an insurance bill. Just an FYI: Progressive will NOT write policies in the Bay Area.

The agents have responded. You can read their comments in opposition of the bill here. They pretty much reflect the talking points provided by Progressive. So take a few minutes to write to the Committee in support of this bill. Here are my talking points:

  • This bill requires the insurance industry to justify rate increases over 10%. If they can’t justify their increases they should not be able to increase.
  • This bill is the least our elected officials can do for those affected by the rising cost of home insurance. Literally.
  • This bill will NOT address the problem of our out of control insurance premiums
  • Justifying an increase in rates will NOT lower premiums since premiums are calculated based upon the rates and other factors
  • Our issue in the Bay Area is the extreme premiums and deductibles.

Your comments would be appreciated 
On Monday 5/19/25  the House Insurance Committee will hear Senate Bill 1643. This bill will require insurance companies to justify to the Texas Department of Insurance any rate increase above 10%. It DOES NOT regulate the rate, it simply requires a justification.

The Industry has sent out emails to their insurance agents to write comments opposing this bill and they have. You can also send in comments. It is easy. The form is online here. Do the following:

  • Fill out your personal information
  • Select SB 1643 by Schwertner
  • Enter your comments including your support for the bill
  • Submit your comments

Again thank you for your interest in this issue!


Insurance Company Asks for Help from Bay Area Homeowners (LOL)

May 14, 2025

Progressive Insurance sent out a message to home owners and insurance agents in the Bay Area urging them to contact elected officials concerning an insurance bill. Just an FYI: Progressive will NOT write policies in the Bay Area.

Senate Bill 1643 will require an insurance company to justify their rate increases of more than 10% prior to using the new rates. Back in 2003 the Legislature removed the prior approval of rate increases and implemented a “File and Use” system allowing the insurance industry to raise rates, file them with the Texas Department of Insurance (TDI), and immediately use the new rates. The rates could be challenged by TDI but they rarely do.

Needless to say the insurance industry is whining like a two year old, sending out emails to their agents and homeowners doing what they have been doing for the last 20 years, complain about turning into California with rate regulations. If they lived in the Bay Area they would realize that we ARE California! Rates have skyrocketed and deductibles are through the roof. Many companies including Progressive, will NOT write policies in the area. Their great “Free Market” lets them Flee the Market and they have. All the bill requires is justification for raising rates above 10%. If you can’t justify it, you shouldn’t be using it. It’s not regulating squat.

The hearing for the bill was scheduled in the House Insurance Committee has been canceled.


Texas Insurance Legislation: A Disappointment for Bay Area Property Owners

May 6, 2025

We are on our own until November 2026.

Side Sour Note: 
Since my visit to Austin I have been overly busy and have neglected to keep you informed of the progress of any bills that may help us with the rising cost of insurance. I left Austin extremely disappointed in the lack of attention to our situation. Let me be blunt about where we stand. No one is coming to help us. The bills being debated are nothing but minor changes that will NOT help reduce our premiums. There are some Legislators who understand our situation and are trying but they are overwhelmed by the opposition in Austin. Where do we go from here? I do not know.

Bills being debated:
Megan Kimble of the Houston Chronicle just wrote an excellent article, “Texas plan to rein in home insurers doesn’t go far enough”  concerning a number of bills making their way through Austin. Take some time to read it to understand where we stand.

Our State Representative and Senator
HB2067/SB1006. State Representative Dennis Paul and Senator Mayes Middleton filed HB2067 and SB1006 which are “companion” bills. Companions make it easier to fast track. Both are on their way to passing but will have no effect on our situation. The bills require an insurance company to write a letter when they cancel or deny service to you. That’s all it does. Expect them to boast about this accomplishment soon after the session is over.

Senator Mayes is stepping away from his seat to run for Texas Attorney General and Dennis Paul is rumored to be retiring. Maybe we can find two candidates who will champion our cause in 2026.

HB2741 will prohibit the use of credit scoring in setting premiums. It was left pending in the Insurance Committee in early April. SB1644 Will require an insurance company to write a letter if your credit score negatively affects your premiums. It seems ready to pass. Once again pretty useless.

SB1643 will require insurance companies to justify an increase in a rate over 10%. It passed the Senate. This bill does NOT apply to increases in premiums. It is for rate increases. Your rate may not change but your premium might double. This bill does absolutely nothing for us. 

HB1576/SB2924 will create a “Fortify” program similar to Alabama. In Alabama the state helps you fortify your home from weather events in exchange for lower premiums. The Texas bill does not guarantee lower premiums. Why anyone would go through the expense of fortifying a home without an incentive is beyond me. The House bill has passed the house. The Senate bill is coming up for a hearing.

No bills were filed to address the cost of repairs or price gouging after a weather event.


Recap on home insurance bill hearing. (It’s not good)

March 28, 2025

Our Representative, Dennis Paul, filed HB 2067. The hearing for HB 2067 was held on Tuesday March 26 starting at 8:00 am in Austin. The bill will simply require an insurance company to write a letter to a policy holder if they deny or cancel their policy. That’s it. Nothing more. It will NOT lower our premiums or deductibles. 

You can view the entire hearing here. It starts at 1:30 and runs for about 15 minutes.  I spoke with every staff member responsible for the bills in the Insurance Committee and urged them to, at the very least, require the insurance companies to report this information to the Texas Department of Insurance so we can know what companies do not do business in our area. That was not discussed in the hearing. I also met with Representative Paul last week concerning this issue.

At the end of the hearing a member of the TDI touched on the lack of this data being available to the consumers but unless a bill addresses this issue nothing will be done. This bill does not address this issue.

Thank you for sending your comments to the committee. There are other bills being addressed. I will keep you informed.

Dennis Pauldennis.paul@house.texas.gov512-463-0734

Contact Your Representatives on Insurance Bill Now

March 22, 2025

Do something!

Our Representative, Dennis Paul, filed HB 2067. The hearing for HB 2067 is scheduled for Tuesday March 26 starting at 8:00 am in Austin. The bill will simply require an insurance company to write a letter to a policy holder if they deny or cancel their policy. That’s it. Nothing more. It will NOT lower our premiums or deductibles. Contact the members of the committee and voice your concerns. (Talking points below)

Register your comments on the Insurance Committee website. It’s easy!

Then send your comments to the following with the subject line Comments on SB1006. You can also call and and ask to talk with someone about HB2067 in the Insurance Committee. Send it to the following:

Contact InformationNameEmailPhone
Jay Dean (Chair)jay.dean@house.texas.gov512-463-0750
Hubert Vo (Vice Chair)hubert.vo@house.texas.gov512-463-0568
Dennis Pauldennis.paul@house.texas.gov512-463-0734
David Spillerdavid.spiller@house.texas.gov512-463-0526
Jessica Gonzalezjessica.gonzalez@house.texas.gov512-463-0408
Vikki Goodwinvikki.goodwin@house.texas.gov512-463-0652
Andy Hopperandy.hopper@house.texas.gov512-463-0582
Matt Morganmatt.morgan@house.texas.gov512-463-0710
Trey Whartontrey.wharton@house.texas.gov512-463-0412
Greg Bentchgreg.bentch@house.texas.gov512-463-0734

Easy cut and paste email addresses:
jay.dean@house.texas.gov
hubert.vo@house.texas.gov
dennis.paul@house.texas.gov
david.spiller@house.texas.gov
jessica.gonzalez@house.texas.gov
vikki.goodwin@house.texas.gov
andy.hopper@house.texas.gov
matt.morgan@house.texas.gov
trey.wharton@house.texas.gov
greg.bentch@house.texas.gov

Here are some talking points:

  • We are in dire need of premium and deductible relief.
  • This bill will not reduce our premiums
  • This bill will not make our deductibles reasonable
  • At the very least this bill should require the insurance companies to report denial of service to the Department of Insurance and make this information public.

Report: Meeting with Texas Representatives on Insurance Issues

March 15, 2025

A Report from Austin 
(BTW halfway through my visit I received my renewal notice. My home insurance increased from $6000 to $9000) 

Last week I was joined by another homeowner from the Bay Area at the Capitol (Thanks Doug). We were able to talk with the staff of most of the members of the House Insurance Committee concerning the rising cost of home insurance in our area. The bottom line? I don’t think they understand the severity of the situation here in the Bay Area..

We were able to meet with our State Representative Dennis Paul and his Chief of Staff. As you may know Representative Paul lives two blocks from me and he had his roof replaced after the hail in May so he must know what we are going through but our conversation was not what I expected. He had a lot of excuses for the rising cost of insurance including inflation, supply chain issues, and lawsuit abuse. All of these combined could not account for excessive rates in our area. These are  talking points used by the insurance industry. They also talked very briefly about “climate change” or as they call it “frequency and intensity of storms)

We made sure they were aware of the excessive cost of repairs which directly affect our premiums. Roofs replacements after a storm should not  cost $32,000 in our area especially when that roof would cost only $8000 under normal conditions. (My estimate was $24,000 and was submitted as $40,000 to my insurance company)

We discussed the fact that the “Free market” is letting the insurance industry free to leave the market. The top 6 companies in Texas will NOT write policies in our area. We are now being pushed into a socialized market run by the State, the Texas Fair Plan, which is not fair.

We provided some solutions like using better building materials, automatic cutoff valves for water pipes, the use of metal roofs. 

I have provided the letter we left with them below. I will have a list of bills affecting our insurance premiums early next week.


Senate Bill 1006 Hearing concerning Insurance Cancellations

March 8, 2025

The Business and Commerce held a hearing on Senate Bill 1006 filed by our Senator Mayes Middleton. I’ve been critical of the bill since all it will do is require an insurance company to send a letter to explain why they canceled your policy or denied you service. It does NOT require this information to be provided to the Texas Department of Insurance and made available to the public. You can view the entire meeting here starting at 1:19:30. Here is a recap:

  • The insurance companies are NOT in favor of this simple bill.
  • The insurance companies already are required to provide this information IF you ask.
  • Senator Zaffarini asked if this information concerning cancellations and denials are being collected by TDI. (They are not) The Houston Chronicle wrote a story on this problem.
  • FYI. The members of the Texas Coalition for Affordable Insurance Solutions, Allstate, Farmers, Farmers Bureau, USAA, Nationwide, and State Farm will NOT write new policies in our area.
  • This letter could help homeowners fight the insurance company if the reason for denial contains false information.

Hearing set for an insurance bill tomorrow. Send comments!

March 3, 2025

Get off your butt and do something! It is easy.

Our Senator Mayes Middleton filed SB1006. The hearing for SB1006 is scheduled for Tuesday March 4 starting at 10:00am in Austin. Our State Representative Dennis Paul filed a “companion” bill which is an exact duplicate. The bill will require an insurance company to write a letter to a policy holder if they deny or cancel your policy. That’s it. Nothing more. It will NOT lower our premiums or deductibles. Please send comments to the following with the subject line Comments on SB1006. Click here to email each. You can also call and and tell them you want to talk with someone about SB1006 in the Business and Commerce Committee. Send it to the following:

Senatoremail phone
Charles Schwertnercharles.schwertner@senate.texas.gov512-463-0105
Phil Kingphil.king@senate.texas.gov512-463-0110
Cesar Blancocesar.blanco@senate.texas.gov512-463-0129
Donna Campbelldonna.campbell@senate.texas.gov512-463-0125
Brandon Creightonbrandon.creighton@senate.texas.gov512-463-0104
Nathan Johnsonnathan.johnson@senate.texas.gov512-463-0116
Lois KolkhorstLois.Kolkhorst@senate.texas.gov512-463-0118
Jose Menendezjose.menendez@senate.texas.gov512-463-0126
Robert Nicholsrobert.nichols@senate.texas.gov512-463-0103
Judith Zaffirinijudith.zaffirini@senate.texas.gov512-463-0121
Mayes Middletonmayes.middleton@senate.texas.gov512-463-0111

Easy cut and paste email addresses:
charles.schwertner@senate.texas.gov
phil.king@senate.texas.gov
cesar.blanco@senate.texas.gov
donna.campbell@senate.texas.gov
brandon.creighton@senate.texas.gov
nathan.johnson@senate.texas.gov
Lois.Kolkhorst@senate.texas.gov
jose.menendez@senate.texas.gov
robert.nichols@senate.texas.gov
judith.zaffirini@senate.texas.gov
mayes.middleton@senate.texas.gov
matt.patterson@senate.texas.gov

Here are some talking points:

  • We are in dire need of premium and deductible relief.
  • This bill will not reduce our premiums
  • This bill will not make our deductibles reasonable
  • At the very least this bill should require the insurance companies to report denial of service to the Department of Insurance and make this information public.

UPDATE: Bills addressing the rising cost of home insurance

February 6, 2025

Don’t get excited.

Bills addressing the rising cost of home insurance have been filed by our elected officials representing the Bay Area. Unfortunately the bills do not address the rising cost of home insurance. Here is a summary and contact info for our elected officials:

House Bill 2067 HB2067 is filed by our State Representative Dennis Paul. It will require an insurance company to provide to the policyholder a written statement on the reasons for nonrenewable or cancellation of a policy. This bill does NOT require the companies to report this information to the Texas Department of Insurance. Megan Kimble of The Houston Chronicle wrote an article about this cancellation data not being recorded by TDI. The bill will NOT reduce premiums or deductibles. I just don’t see the value of this bill.

Senate Bill 1006. SB1006 is filed by our State Senator Mayes Middleton a “companion bill”. It is the same as HB2067 and is filed to expedite its passing.

House Bill 2067. HB2067 is a bill filed by Representative Oliverson establishing a grant program to “fortify” homes against windstorm damage. This is promising but unlike the Alabama program created 15 years ago does not guarantee a reduction in premiums if a homeowners fortifies their home.

Contact our elected officials about these bills Please send a quick email and call our State Representative Dennis Paul and State Senator Mayes Middleton via their staff Greg.Bentch@house.texas.gov (512) 463-0734) and Matt.patterson@senate.texas.gov (512) 463-0111) respectfully.

Ask for a response. Ask how these bills will reduce your premiums, make deductibles reasonable without the loss of coverage or rights.


CliffNotes: State Affairs interim report on home insurance

January 27, 2025

I’ll save you the trouble of reading 4 pages.

The Texas House State Affairs Committee was charged to “Examine the impact of current economic challenges on the escalating costs of insurance premiums“. They held a hearing with invited testimony only. Many consumers, especially in this area, contacted the committee. I don’t think it helped. Here is a summary. The full report can be read here starting on page 70.

  • Only invited testimony was allowed including a lobbyist from the Texas Coalition for Affordable Insurance Solutions representing the top 6 insurers in the state.
  • In 2003 Texas adopted a “file and use” system allowing insurance companies to raise rates without prior approval from the Texas Department of Insurance (TDI)
  • TDI has the rights to disapprove the rate increases but has rarely used this right
  • Climate change is being blamed for high insurance rates disguise as “Frequency of storms” and “Intensity of storms”
  • 60-70% of all premiums are used to pay out claims.
  • AARP testified concerning the hardship being placed on the elderly on fixed incomes
  • Oncor stated their insurance went from $10 Million to $60 Million in just a few years. This is passed on to consumers
  • Insurance companies are complaining about “reinsurance” which I believe is insurance for insurance companies.
  • Texas is NOT addressing non-renewals. They are not collecting this data. 5 of the 6 companies in the TCAIS will not cover the Bay Area
  • 4 Companies, including Progressive, have left the state
  • Legislators are concerned about the lack of transparency in rate increases

Recommendations:
This is disturbing. The outrageous cost of roofing after an event such as hail or a storm was not mentioned. There is evidence of price gouging concerning construction cost. They need to address it.

The recommendations included “Promote Risk Mitigation Programs:” such as the Fortify program Alabama adopted 15 years ago. A water downed bill has been filed on this issue.

They recommend providing tax funded backup to insurance companies to keep them in Texas. That doesnt make sense especially when they also recommend phasing out the Texas Windstorm Insurance Association (TWIA) and the Texas Fair Plan to allow the industry to provide these services. (They do NOT want to provide these services)

They also recommend educating homeowners and placing a surcharge on all insurance companies to pay out disaster claims.

As I said about the Senate report. This was underwhelming.


Movie Review: The Substance starring Demi Moore

January 25, 2025

Watch it? Rent it? Skip it?

SKIP IT! Do yourself a favor. If you just have to see Demi Moore naked wait till it is streaming free then go clean the toilets. You will get more from cleaning the toilet than watching this movie.

That was $5.99 down the drain. What an incredibly stupid, meaningless, gross movie. If I could sue someone for the $5.99 I spent watching this I would. An interesting plot at first that fell into a gross set of scenes that got dumber and dumber as the movie progressed. Demi Moore was OK but not great. Her nakedness did not help. The 4k did her no favors what so ever. I fell asleep during the middle but unfortunately woke up for the finale that was just gross, ridiculous, and just plain stupid. It was like a jr high school film project. I feel stupid just admitting I watched it.

Rotten Tomatoes had an 89% rating and an audience rating of 75% on this film. What the living hell they watched is beyond me. That movie should end Demi Moore’s comeback tour.


Raising Campaign Cash: State Representative Dennis Paul

January 17, 2025

Not promising for us concerned about home insurance.

State Representative Dennis Paul raised $55,905 in his latest reports covering the period of July-December 2024. That actually is one of his most productive reports. Of that total $54,600 or 98% came from PAC money and $1,304 came from 6 individual donors. Of these $8500 came from insurance related PACs. Paul sits on the House Insurance Committee.

During the same period he spent $39,049 with $22,500 going back to a number of PACs including Realtor PACs, USAA, General Contractors PAC, and BearBacker PAC. $15,000 went to pay off his outstanding $150,000 loan to win the seat over 10 years ago. He received $2500 from the BearBacker PAC then turned around and donated $2500 back to them. BearBacker PAC is related to the Baylor Bears according to their Facebook page.


Cliffnotes: Interim Report on Insurance from the Business and Commerce Committee

January 3, 2025

Underwhelming to say the least.

If you would like to read the report on the interim charges to the Texas Senate Business and Commerce Committee it is available online here starting on page 19. It is interim charge 7 titled “Addressing the Rising Cost of Insurance. It is only 2 pages. Here are my notes/thoughts.

  • The Committee held a hearing on Oct 1. The testimony was dominated by the industry.
  • Texas has the 2nd largest market in the nation bringing in $290 Billion in premiums.
  • The increase in premiums are due to climate change, inflation, labor expenses, supply chain disruptions and reinsurance (LOL. They are using climate change against us to increase our premiums. Inflation is well under control and has been for a while but it did NOT account for a doubling of premiums. Supply chain disruptions were corrected years ago.)
  • They ignored the inflated cost of roofing after an event such as hail or extreme weather. Why does a roof cost $24,000 to replace after an event, but only $6000 at other times?
  • They blame us for not “shopping around”.
  • TDI stated only 4 companies left Texas in 2024 but ignored comments from area such as the Bay Area where 5 of 6 members of the Texas Coalition for Affordable Insurance Solutions (TCAIS) will not longer write policies.
  • There was a significant uptick in the Texas Fair Access to Insurance Requirements (FAIR) Plan from 72,626 to 91,841 from 2003 to 2024.
  • TDI claims homeowners in Texas saw an average rate increase of 21% in 2023. I’m not sure if that is a rise in rates or premiums which are two different things.
  • TDI reviewed 1313 rate filings with 107 filings withdrawn, 78 rejected for administrative discrepancies. They did not disclose how many rate increases were rejected by TDI.
  • The recommendations are basic if not ridiculous.
    • Implement guardrails to protect against unfair pricing practices, which could include, but is not limited to, rate filings and premiums assessed to policyholders.
    • Support the efforts of both TDI and OPIC to improve notice to policyholders about rate changes, coverage reductions, and comparison-shopping tools.


Community Meeting on the rising cost of Home Insurance

January 2, 2025

I have secured the Webster Activity Center on Jan 7, 2025 for another community meeting to discuss and take action concerning the rising cost of home insurance in our area. We will focus on the upcoming legislative session and how we can take the opportunity to influence our elected officials. For those who are not aware this session begins Jan 14 and will continue till June 2

Our elected officials have been invited to attend and discuss what we can do. Please save the date, invite your neighbors, and I will see you Tuesday. Preliminary agenda:

  • Short recap of the last meeting
  • Update on upcoming legislation
  • How can we participate in the process
  • Open forum, Q&A

Join our newsletter at www.tinyurl.com/BayAreaHouston

Tuesday Jan 7, 2005 6:00PM-8:00PM
Webster Activity Center
311 Pennsylvania Ave
Webster Texas 77598


2025 The year of Luigi?

December 31, 2024

Violence is never an acceptable response. (except for Jan 6 according to the Republic Party)

What could possibly drive someone to killing? Many years ago during a hearing in Austin I was describing what homeowners experienced during their fight with their homebuilder concerning a major construction defect in their new home. I had experienced this frustration dealing with my own defect back in 1992. It’s not fun watching as someone with the power to make things right turn to their team of attorneys and ignore you. It’s not fun looking for help from the court system just to learn the builders are well protected by the laws that were originally designed to protect you. It can eat on you and I can see someone being driven to violence. (I had my own thoughts about doing something but it was not violent)

Well years later a man in Georgia after arguing with his homebuilder for over 6 months invited him back to his house and killed him. He served 10 years in prison. Luigi Mangione did the same thing taking the life of an insurance company CEO. He took matters into his own hands much like the Jan 6 rioters. According to trump the rioters were justified because they thought the election was rigged. (hum….who in the living fuck convinced them of that?) Maybe trump will pardon Luigi since he believed his violence also justified.

Maybe others will get the idea of taking advantage of our lax gun laws and solve their problems with their God given right to the 2nd Amendment. America is poised to bring back western style justice against those who harm them financially or physically. When the criminal and civil courts abandoned you and you are left with only memories of a loved one, or left with the job of taking care of a loved one for the rest of their life, or left in financial ruin and you have easy access to military style firearms what could possibly go wrong for those who are responsible? Top that off with elected officials on every level of government condoning violence as they did on Jan 6.

Maybe Luigi did us a favor, but in the wrong way. Maybe CEO’s might want to think twice about screwing people. Maybe homebuilders might want to fix the defects they created. Maybe law makers might want to create laws to protect us from gun violence instead of offering useless thoughts and fucking prayers.

In America those who take the law into their own hands usually end up being held accountable….except for trump’s Jan 6 rioters. So America, stand back and stand by.


Movie Review: Homestead

December 23, 2024

Watch it? Rent it? Skip it?

For fuck sakes. Skip it. That was a complete waste of 2 hours. Great idea, stupid script, poor acting, incredibly dumb plot. This movie is the complete package. It has a load of paranoia by a bunch of government hating, gun toting, former military, bad acting, survivalists who sees an opportunity after a nuclear bomb hits Los Angelos and takes out the grid across the country. People flock out of the Los Angeles area running to the hills looking for someone who has food, water and shelter. Many camp out at the gates of a property in Colorado who just happens to have food, water, and shelter but won’t let them in. This is where the movie remains.

The worst part of the movie is when the wife of the property owner ends the show with having faith in god to bring peace and love and joy and more food, water, and a fuckin TV show once in a while. OMG it is so corny. God will fix it all just like he fixed Los Angeles, just prior to being blown off the goddamn map.

It’s an incredibly stupid movie but has an after credit that is not worth watching because this is the beginning of a series. One of the gun toting, government hating, bad acting, survivalists asks that you scan a QR code on the scree to view the 1st episode of the new series.

Just don’t do it. This is just a stupid ass movie.


The cost of price gouging after a weather event. Bags of ice. Gasoline. Roof repairs.

December 19, 2024

And you wonder why your insurance premiums are so high?

I filed a claim for roof damage after Hurricane Ike in 2008. I received about $5000 from USAA, my insurance company at the time. Bids for the roof replacement ranged from $10,000-$16,000. At the time I did not have the extra funds to pay for the roof and since there was no leaks I put the repairs off for 2 years.

In 2010 I had my roof replaced for $4800. One of the companies that quoted over $10,000 in 2008 provided a quote of $6800 in 2010. At the time I knew the Commissioner of the Texas Department of Insurance and mentioned the price gouging after a hearing in Austin. Soon afterward he left the Commission and I ended my consumer activism.

So here we are in 2024 and I filed a claim for hail damage. Eventually I had my roof replaced for a cost that was listed at $24,000 about 5 times what I paid in 2010 just 14 years ago. I’ve heard from others in my subdivision whose estimates were even higher, $32,000 for one homeowner. What is disturbing is that the insurance companies are paying these inflated prices. It’s a win-win for the roofer and the insurance company who can simply pass the inflated cost to consumers in higher premiums. Everyone is happy except for the consumer.

Last year Harris County Attorney filed a number of suits resulting in settlements for price gouging of gasoline. According to Houston Public Media:

The Bellaire location allegedly sold regular unleaded gasoline for $3.79 and $4.29 per gallon, an increase of 25% and 41% respectively from the gas station’s pre-hurricane price of $3.03. The Baytown location was allegedly selling premium gasoline for $5.49 per gallon, which is 44% higher than the gas station’s pre-hurricane price of $3.80.

Price gouging after an event like a hurricane is illegal. Raising the cost of a gallon of gas by 40 cents can be considered price gouging and could be investigated by the County Attorney. Charging 2 to 4 times the regular price for a roof should be considered price gouging.

I’ve asked the County Attorney to investigate.


Texas Homeowners Left Behind: The Insurance Crisis

December 18, 2024

This should really piss you off.

Sixteen years ago States along the coast began implementing a plan called Fortified, including Alabama. According to an article written by Megan Kimble of the Houston Chronicle: “Alabama offers $10,000 grants to homeowners to upgrade their roofs – and requires insurers to give discounts of 25% to 55% to those who do”. That program started 16 years ago!! What the hell did elected officials in Texas do?

Nothing. Not a goddamn thing and now we are paying for it. Literally. We are now in crisis mode with premiums out the roof, excessive deductibles, and companies threatening to leave the Sate. In the upcoming legislative session bills will be filed to protect the insurance industry at our expense. While other States were actively working to lower the risk our elected officials did nothing to protect our homes. This article is another in her series concerning home insurance. It’s a VERY good read. I should be available to read here. It might make you mad. Let me summarize:

  • While other states on the coast, like Alabama, took action 15 years ago to reduce the risk to homeowners, Texas did nothing, at all, except pass the cost of the risk to consumers.
  • Other states give incentives to homeowners to “fortify” their homes and requires reduced insurance premiums.
  • A bill has been filed in Texas to create a program similar to Alabama’s “Fortified” but does NOT require a reduction in premiums
  • Of the country’s 70,000 Fortified homes, only 200 are in Texas and half of those were built by Habitat for Humanity.
  • While Texas officials were busy cutting regulations and chasing social issues we were left to find our own insurance solutions.
  • I love this quote “Home builders along the coast say they already follow stringent building standards and don’t need more.”
  • “In coastal Alabama and North Carolina – both states that incentivize Fortified standards – researchers say homes certified through the program have shown a 20% reduction in losses compared to non-Fortified homes.”
  • Alabama offers $10,000 grants to homeowners to upgrade their roofs – and requires insurers to give discounts of 25% to 55% to those who do. That program started 16 years ago!!

So take some time to read the article then make plans to attend our next meeting.


The Rising Cost of Insurance. CCISD

December 16, 2024

This isn’t right.

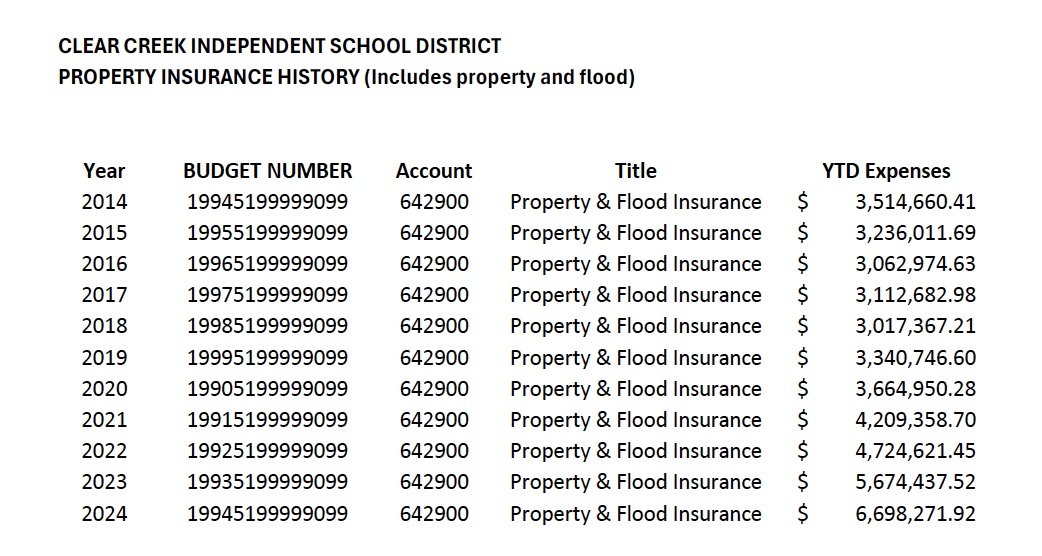
As said before the rising cost of property insurance is affecting everyone in the Bay Area, including taxpayers. According to an open records request CCISD’s property insurance doubled in just five years from 2019-2024. In 2019 CCISD’s property and flood was $3.3M. In 2024 it was $6.6M. This is not solely due to inflation. There is much more to this increase than inflation.

Everyone is paying for the rising cost of insurance including homeowners, businesses, government entities and taxpayers. Come join us next year to have a discussion with elected officials.